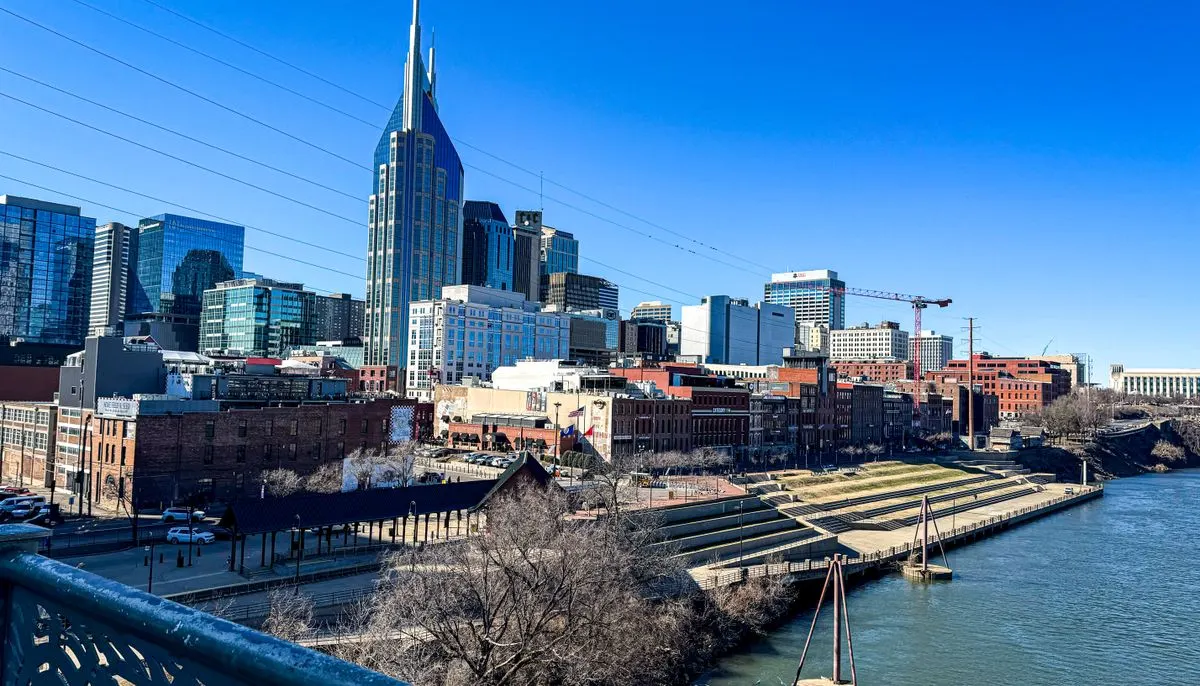
Multifamily construction loans in Nashville are short-term, draw-funded facilities that pay for land, hard costs and carrying interest, then get repaid by a permanent loan or a sale once the building leases up. The pipeline is still substantial: the Nashville metro authorized 5,827 units across 154 buildings in 5+ unit structures during 2025, according to the U.S. Census Bureau's Building Permits Survey. But a sponsor building a small infill project in Donelson faces a different lender set — and a different underwriting conversation — than a group delivering a tower on the East Bank.
This guide walks the process for small and mid-size Nashville multifamily: who lends, how leverage actually gets set, what the 2026 rate backdrop does to your carry, and what repays the loan at the end. For the national mechanics that apply in every market, see our multifamily construction loan guide.
How does a Nashville multifamily construction loan actually work?
A Nashville multifamily construction loan funds in draws against completed work rather than landing in your account on day one, and it charges interest only on drawn balances. You close on land and permits, build against a budget the lender approves, then repay the entire facility with a permanent takeout once the property stabilizes.
That structure has three consequences most first-time sponsors discover late.
Interest is capitalized, not paid from cash flow. There is no rental income during construction, so the lender sizes an interest reserve into the loan budget. If your schedule slips, that reserve depletes and you fund the shortfall out of equity.
Draws are inspected, not simply requested. Each draw requires lien waivers, an inspector's sign-off on percentage complete, and confirmation that the remaining budget still covers the remaining work. That cycle is worth understanding before you close — we break the sequence down in our construction draw schedule guide.
The budget is effectively a covenant. Staying "in balance" means undrawn loan proceeds plus remaining equity must cover the cost to complete. Blow through a line item and the lender can require an equity infusion before releasing the next draw.
Who lends on small Nashville multifamily construction
Four lender categories write ground-up multifamily paper in Nashville, and which one fits depends far more on your deal size, sponsor track record and leverage need than on the address itself. Regional and community banks dominate the small-balance end, debt funds price higher in exchange for speed and leverage, and government-insured programs serve patient sponsors.
| Lender type | Typical fit | What they optimize for | Common friction |
|---|---|---|---|
| Lender type Community and regional banks | Typical fit Smaller ground-up projects, local sponsors | What they optimize for Deposit relationship, recourse, in-market knowledge | Common friction Personal guarantees; slower committee cycles |
| Lender type National banks | Typical fit Larger projects, repeat institutional sponsors | What they optimize for Balance-sheet quality, sponsor liquidity | Common friction Minimum deal size screens out small sponsors |
| Lender type Debt funds and private credit | Typical fit Complex basis, tight timelines, higher leverage | What they optimize for Speed, certainty of execution, structural flexibility | Common friction Higher spread and fees; tighter covenants |
| Lender type Government-insured (FHA/HUD) | Typical fit Long-hold sponsors trading time for terms | What they optimize for Non-recourse, construction-to-permanent in one close | Common friction Long process; program and wage requirements |
The recourse question comes first. Most bank construction debt for small multifamily carries at least partial recourse, typically burning off as the property hits completion and debt-service coverage milestones. Non-recourse generally costs you leverage, spread, or a government-insured program's timeline.
Sponsor experience is priced, not just checked. A sponsor who has delivered comparable projects gets better terms than one who has not, on identical real estate. That gap is often wider than the difference between two lenders' rate sheets.
What LTC can a Nashville sponsor realistically expect?
Loan-to-cost measures your construction loan against total project cost rather than against finished value, so it is the number that decides how much equity you write at closing. In practice the binding constraint is rarely the construction lender's stated appetite — it is whether the stabilized building can support a takeout large enough to repay the facility.
Work the problem backwards. Your permanent loan will be sized by whichever of three tests bites first, and CBRE's data on loans it originated or brokered gives a rough reference for where those tests sat:
- Loan-to-value. Multifamily LTV ratios averaged 63.3% in Q2 2026, down from 65.8% a year earlier, per CBRE.
- Debt service coverage. The average debt service coverage ratio rose to 1.43, up from 1.34 a year ago, CBRE reported.
- Debt yield. Average debt yield improved to 10.2%, from 9.7% over the same period.
If your stabilized net operating income only supports a permanent loan well below your total project cost, then a construction lender offering leverage above that line is handing you a refinancing gap, not a gift. Size the construction facility to what the exit will actually retire, and treat anything above that line as equity you will eventually need to write anyway.
Practical implication: the equity check on a small Nashville ground-up deal is driven by your cost basis and your projected stabilized NOI, not by a headline leverage percentage. Land bought well is the single largest lever a small sponsor controls.
Rates, spreads and the 2026 capital backdrop
Construction loans in Nashville float over SOFR, so the two numbers that set your carry are the index itself and the spread your lender quotes on top of it. SOFR printed 3.68% on August 31, 2026, per the Federal Reserve Bank of St. Louis, and its separate 10-year Treasury constant maturity series closed at 4.73% on August 28, 2026.
That second number matters more than sponsors expect: the 10-year is the benchmark behind most fixed-rate permanent takeouts, so it prices the loan that repays your construction facility. The lending environment behind both rates is competitive. CBRE's Lending Momentum Index stood at 1.0 at the end of Q2 2026, easing from a five-year high of 1.5 in Q1 but still historically elevated. Loan counts rose 11% year-over-year, average commercial mortgage spreads narrowed 21 basis points to 204 bps, and multifamily spreads tightened to 162 bps. Average mortgage interest rates came in at 5.7%, down from 5.9% a year earlier, CBRE reported.
Read those figures together and the picture is specific: lenders are competing on price, not on leverage. Spreads compressed while LTV ratios fell. That is a market where a well-documented small deal can win attractive pricing but will not win a leverage argument. How the same comparison runs across Knoxville, Chattanooga and Memphis is in our Tennessee multifamily construction lender guide.
Who is actually closing. Among CBRE's own non-agency loan closings in Q2 2026, alternative lenders accounted for 38% of volume, banks 30%, life companies 21%, and CMBS 11%. For a small Nashville construction deal, that means banks and alternative lenders are the two realistic conversations to run in parallel. Statewide context sits on our Tennessee market page.
Where the deals are: Nashville submarkets
Nashville's construction lending appetite is not evenly distributed across the metro, and the submarket on your address materially changes both the leverage available and the questions underwriting will ask. Metro population reached roughly 2.2 million, a 14% gain since the 2020 Census, per Commercial Observer — the demand story lenders underwrite against.
East Bank. The corridor anchored by Oracle's campus, tied to roughly 8,500 Nashville-area positions per Commercial Observer, plus the stadium district and associated infrastructure work. Lenders treat this as demand-driven, but supply concentration means underwriting will test your rent assumptions hard against what is already delivering nearby.
Wedgewood-Houston. A mixed-use redevelopment corridor south of downtown where large master-planned projects have reshaped the district. Small infill sites here compete against institutional product on amenities, which pushes small sponsors toward a differentiated unit mix rather than head-to-head competition.
South Gulch. Continued large-scale mixed-use development adjacent to downtown. This is expensive land; small ground-up multifamily generally pencils only where the basis was established years ago, or where the sponsor is building something the towers are not.
East Nashville. An established residential district with meaningful infill opportunity at small scale. This is where small-balance construction lending looks most conventional, and where a community bank relationship carries the most weight.
Donelson and Madison. Older inner-ring areas with airport and interstate access. Basis is lower and rent ceilings are lower too, so the underwriting question shifts from "can you compete on amenities" to "does your cost basis survive a slower lease-up."
The honest framing for any of these: Nashville absorbed a large supply wave, and construction lenders in 2026 scrutinize lease-up risk more carefully than construction risk. Your rent comps matter more than your renderings. Submarket context sits on our Nashville market page.
The construction timeline, draw by draw
A small Nashville multifamily construction deal moves through five distinct phases, and the lender's requirements change completely at each one rather than staying fixed from the term sheet onward. Sponsors usually underestimate pre-closing diligence and post-completion lease-up, not the build itself, because both burn interest while producing no stabilized rental income.
| Phase | What the lender needs | What breaks the schedule |
|---|---|---|
| Phase Term sheet | What the lender needs Sources and uses, sponsor resume and liquidity, rent comps, exit plan | What breaks the schedule Budget that ignores contingency or interest reserve |
| Phase Closing diligence | What the lender needs Appraisal, plans and specs, GC contract, permits, environmental, title | What breaks the schedule Entitlement or permit timing; GC contract not finalized |
| Phase Construction draws | What the lender needs Lien waivers, inspection sign-off, in-balance test at each draw | What breaks the schedule Cost overruns; change orders without lender consent |
| Phase Completion | What the lender needs Certificate of occupancy, final lien waivers, as-built survey | What breaks the schedule Punch-list delays pushing past the maturity date |
| Phase Lease-up to stabilization | What the lender needs Rent roll trending to underwritten occupancy and coverage | What breaks the schedule Slow absorption; concessions eroding effective rents |
Where extensions get expensive. Construction facilities usually include extension options tied to completion and coverage milestones. Missing a milestone converts a cheap extension into a negotiation, and negotiations at maturity are conducted from weak ground.
What takes out the construction loan?
Every construction loan is underwritten backwards from its exit, so your takeout plan is the first thing a Nashville construction lender will interrogate and the last thing you should improvise. The three live paths are an agency permanent loan, a bank or life company permanent, or an outright sale, and agency capacity for 2026 is substantial.
Agency capacity is set annually. FHFA established 2026 multifamily loan purchase caps of $88 billion for each Enterprise, $176 billion combined, requiring at least 50% of each Enterprise's multifamily business to be mission-driven affordable housing, with workforce housing loans excluded from the caps.
Forward commitments remove takeout risk, for a price. Fannie Mae's forward commitment product lets a sponsor lock permanent financing terms during the construction period, with conversion contingent on construction completion and final underwriting of stabilized net cash flow. That certainty costs a good-faith deposit and fees, and it constrains you if the market later moves in your favor.
Bridge is the fallback, not the plan. If the property completes but has not stabilized enough to clear permanent-loan coverage tests, a bridge loan buys lease-up time. It is a legitimate tool, but pricing it into your base case rather than your downside case is how small sponsors quietly lose their margin.
Sponsors comparing Sun Belt construction markets may find our Houston multifamily construction guide useful — the process is similar, the submarket dynamics are not.
The bottom line
Nashville still permits meaningful multifamily volume — 5,827 units across 154 buildings in 5+ unit structures in 2025, per the Census Bureau — and construction capital is available for well-documented small deals. But 2026 is a market where lenders compete on spread and hold firm on leverage, so the sponsor who wins is the one whose takeout math is credible before the first draw is ever funded.
Do three things before you go to market. Fix your cost basis. Build the stabilized pro forma your permanent lender will actually underwrite, not the one that makes the deal work. Then take a complete package to multiple lender types at once rather than sequentially, because a community bank and a debt fund will price identical real estate very differently.
YieldStack is a commercial mortgage brokerage. YieldStack arranges commercial real estate financing nationwide, matching a request against 20,000+ loan programs and returning 5–8 matches, with a median offer in under an hour, from an institutional lender. It is a 5-minute submit. It costs Zero upfront to submit a deal and review offers; YieldStack's broker fee is 0.50–1.00% of the loan amount and is paid only at closing. Every credit decision is made by the lender; YieldStack arranges the introductions and negotiates on the borrower's side, and no loan, rate, or closing is guaranteed. For the local picture see the Nashville market page and the Tennessee market page. Submit Your Deal →