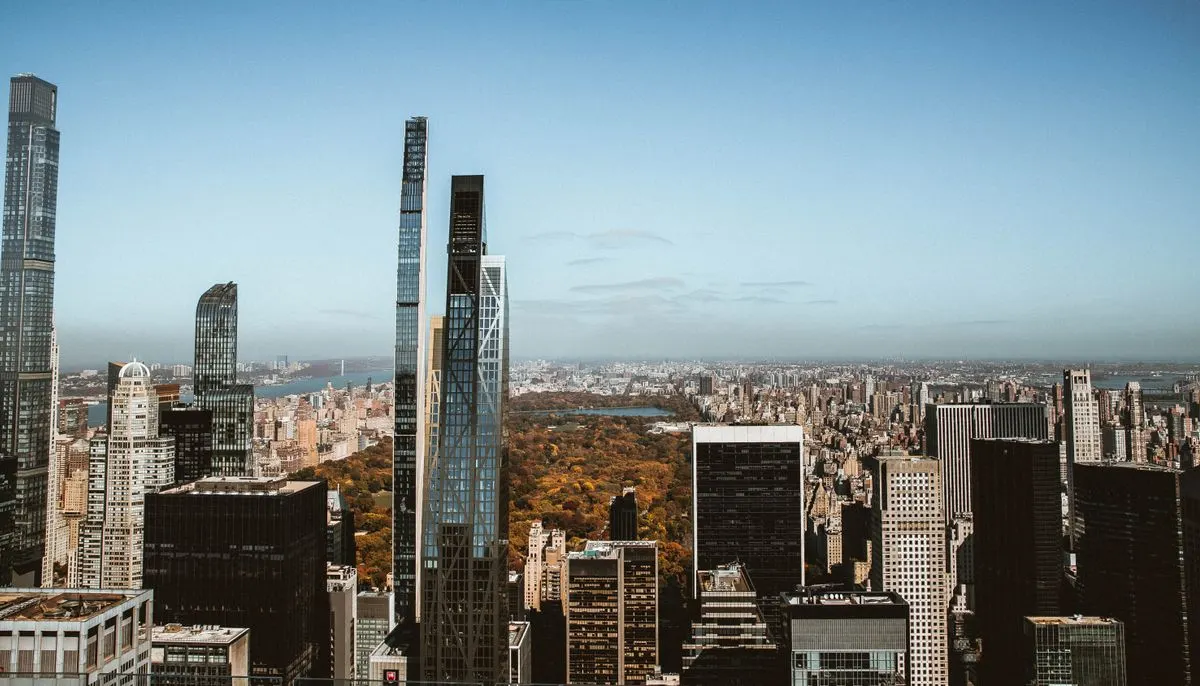
The quick read: You finance a Manhattan office purchase in 2026 with a loan sized on the building's in-place net operating income, tested by debt yield and coverage, and then cut for leases that roll before maturity. Leasing is hot: the Federal Reserve's October 14, 2026 Beige Book reports brisk Manhattan office leasing with bidding wars for top-tier space. The capital side is cooler: in the same report's New York District section, multiple contacts told the Fed that commercial property sales slowed in recent weeks as rising interest rates reduced demand, and small- to medium-sized banks reported that credit standards tightened slightly for commercial mortgages. A buyer who prices the rent roll, the concession package and an office-to-residential fallback under the 467-m tax program before the lender asks gets quotes that compete on proceeds instead of on haircuts.
What do the October 2026 Fed and third-quarter leasing data show for Manhattan?
Third-quarter 2026 leasing data show Manhattan office availability at its lowest since 2020, while the Fed's October 14 Beige Book says small- to medium-sized banks in the New York District tightened standards slightly for business loans and commercial mortgages: Avison Young's third-quarter report, via CRE Daily, puts availability at 13.4%, down 290 basis points.
The leasing numbers are strong. Avison Young's third-quarter report, via CRE Daily (October 5, 2026), says new direct leases averaged $99 per square foot over the trailing 12 months through September, up 28% year over year, while average base rents rose 23% to $120 per square foot. Availability fell to 10.1% in Trophy buildings, 10.0% in the Midtown Core and 3.7% in Hudson Yards. Commercial Observer, via CRE Daily (October 12, 2026), puts third-quarter vacancy at 12.6%, down from 13.1% in the second quarter and 14.7% a year earlier. Vacancy and availability are different measures, so quote each with its own label.
The New York City Comptroller's July 17, 2025 fiscal note on office conversions found that occupied space in 5-star buildings, about 10 percent of all office space, grew by approximately 11.5 million square feet while it declined by 43 million square feet in the rest of the market between the fourth quarter of 2019 and the first quarter of 2025. Avison Young's third-quarter report, via CRE Daily (October 5, 2026), says the improvement in lease economics is increasingly extending beyond Trophy buildings. For a Class B purchase, the lender wants to see that improvement in your own rent roll.
The credit side is tighter. The New York District section of the October 14, 2026 Beige Book says multiple contacts reported that commercial property sales slowed in recent weeks, as rising interest rates reduced demand. Its banking paragraph says small- to medium-sized banks reported flat demand for commercial mortgages, that credit standards tightened slightly for business loans and commercial mortgages but were unchanged for other products, and that delinquency rates moved slightly higher. Nationally, Trepp's September 2026 delinquency report, published October 2, puts the office CMBS delinquency rate at 12.16%, up 16 basis points, and the overall CMBS rate at 8.02%, its highest level since November 2020.
Rates moved against buyers through the year. Treasury's Daily Treasury Par Yield Curve Rates put the 10-year yield at 5.15% on October 19, 2026, against 4.19% on January 2, 2026 and 4.00% on October 20, 2025. In its September 16, 2026 statement, the Federal Open Market Committee raised the federal funds target range by a quarter point to 3.75% to 4.00%, effective September 17.
10-year Treasury par yield (U.S. Treasury, observation date October 19, 2026): 5.15%
Federal funds target range (FOMC implementation note, effective September 17, 2026): 3.75% to 4.00%
Manhattan office availability, third quarter 2026 (Avison Young via CRE Daily, October 5, 2026): 13.4%
Manhattan office vacancy, third quarter 2026 (Commercial Observer, via CRE Daily, October 12, 2026): 12.6%
U.S. office CMBS delinquency rate, September 2026 (Trepp, October 2, 2026): 12.16%
Table: Manhattan office datapoints and what each means for an acquisition loan
| Datapoint (Manhattan unless noted) | Date | Source | What it means for the loan |
|---|---|---|---|
| Datapoint (Manhattan unless noted) New direct leases averaged $99/SF over the trailing 12 months, up 28% | Date October 5, 2026 | Source Avison Young, via CRE Daily | What it means for the loan Supports a market-rent rollover assumption; in-place income still sets the opening loan |
| Datapoint (Manhattan unless noted) Third-quarter 2026 availability 13.4%, down 290 bps, lowest since 2020 | Date October 5, 2026 | Source Avison Young, via CRE Daily | What it means for the loan Evidence for shorter downtime on expiring space |
| Datapoint (Manhattan unless noted) Class A and Class B/C net effective rents comparable at about $83/SF despite a $10 base-rent gap | Date October 5, 2026 | Source Avison Young, via CRE Daily | What it means for the loan Underwrite net effective rent after concessions, not face rent |
| Datapoint (Manhattan unless noted) Third-quarter 2026 vacancy 12.6%, from 14.7% a year earlier | Date October 12, 2026 | Source Commercial Observer, via CRE Daily | What it means for the loan Market support for the appraisal's vacancy line |
| Datapoint (Manhattan unless noted) New York District contacts: commercial property sales slowed in recent weeks as rising rates reduced demand; credit standards tightened slightly for commercial mortgages | Date October 14, 2026 | Source Federal Reserve Beige Book | What it means for the loan Expect tighter proceeds and more structure, so price it before the term sheet |
| Datapoint (Manhattan unless noted) Office CMBS delinquency 12.16% (national) | Date October 2, 2026 | Source Trepp | What it means for the loan The national office credit backdrop every lender reads |
| Datapoint (Manhattan unless noted) 10-year Treasury par yield 5.15% | Date October 19, 2026 | Source U.S. Treasury | What it means for the loan A higher base rate lowers coverage-constrained proceeds |
| Datapoint (Manhattan unless noted) 5-star occupancy up about 11.5M SF, rest of market down 43M SF (Q4 2019 to Q1 2025) | Date July 17, 2025 | Source NYC Comptroller | What it means for the loan Building tier matters more than the borough average |
How do lenders size a Manhattan office loan in 2026?
Lenders size a Manhattan office acquisition loan by running several tests on the building's net operating income, usually debt yield, debt service coverage and loan-to-value, and lending the smallest result, so in a high-rate year coverage or debt yield can bind well before the appraisal does, and rollover reserves come out of what is left.
The Office of the Comptroller of the Currency's Commercial Real Estate Lending handbook (version 2.0, March 2022) defines debt yield as net operating income divided by the loan amount, expressed as a percent. It calls the measure independent of the interest rate, amortization period and capitalization rate, and says debt yields that reflect normalized or higher-rate levels can be used to set stressed loan amounts. The same handbook defines the debt service coverage ratio as net operating income divided by annual debt service, and says properties with volatile cash flows may warrant a higher ratio. Run your own building through the debt yield calculator.
Illustrative example (our arithmetic, not a quote or a lender offer): a 150,000-square-foot Midtown office building produces $7.5 million of in-place net operating income. The debt yields and the 7.00% interest rate below are assumptions chosen to show the slope. They are not market quotes or lender minimums, and the example sets no purchase price, so it implies no cap rate.
Table: Illustrative loan sizing on $7.5 million of in-place NOI
| Sizing test (illustrative inputs) | Maximum loan |
|---|---|
| Sizing test (illustrative inputs) Debt yield of 9% | Maximum loan $83.3 million |
| Sizing test (illustrative inputs) Debt yield of 10% | Maximum loan $75.0 million |
| Sizing test (illustrative inputs) Debt yield of 11% | Maximum loan $68.2 million |
| Sizing test (illustrative inputs) 1.25x coverage, interest-only at 7.00% | Maximum loan $85.7 million |
| Sizing test (illustrative inputs) 1.25x coverage, 30-year amortization at 7.00% | Maximum loan $75.2 million |
| Sizing test (illustrative inputs) 10% debt yield if 30,000 SF at $75/SF goes dark | Maximum loan $52.5 million |
Two inputs move the answer more than the coupon. First, amortization: on these assumptions, a 30-year schedule cuts coverage-based proceeds by about $10.6 million against interest-only. Second, the income the lender accepts. If 30,000 square feet leased at $75 a foot vacates and the lender sizes on the remaining $5.25 million, the same 10% debt yield supports $52.5 million, about $22.5 million less. That gap is the price of rollover.
The loan-to-value test runs on the lender's appraisal, so bring the lease and sales comparables that support your price.
How do lease rollover and concessions change a Manhattan office loan?
Lease rollover and concessions change a Manhattan office loan because lenders count the cost of re-leasing expiring space, including leasing commissions, tenant improvements and free rent, against the cash the building produces, and in a market where landlords compete on concessions, two leases with the same face rent can carry very different net effective rents.
The OCC handbook says office lease terms typically run three, five or seven years. It says leasing commissions are calculated as a percentage of total lease payments, with typical underwriting assumptions of 4 percent for new leases and 2 percent for renewals, and that tenant improvement expenses are higher for new tenants than for renewing tenants and vary widely by market and building class. It says re-leasing costs can be projected from the rent roll with an assumption about the probability of renewals, and that they are not always treated as an operating expense in net operating income but matter when analyzing cash flow.
Concessions are where Manhattan's numbers diverge. Avison Young's third-quarter report, via CRE Daily (October 5, 2026), finds that Class A and Class B/C space deliver comparable net effective rents of about $83 per square foot despite a $10 per square foot gap in base rents, a result Avison Young says reflects "materially different concessions." Expect the lender to convert face rent to net effective rent, so a lease that looks strong on the rent roll can underwrite weaker once its free rent and work letter are deducted.
Illustrative rollover math (our arithmetic, assumptions labelled): take the 30,000 square feet from the example above, leased at $75 a foot and expiring in year two. Assume a 10-year term at the same rent whether the tenant renews or a new tenant signs, a 60% chance of renewal, tenant improvements of $50 a foot on a renewal and $120 on a new lease, four months of free rent on a renewal and 12 on a new lease, and nine months of downtime if the tenant leaves.
Leasing commissions, probability-weighted (OCC's 4% new and 2% renewal assumptions on $22.5 million of lease payments): $630,000
Tenant improvements, probability-weighted (assumed rates): $2,340,000
Free rent, probability-weighted (assumed months): $1,350,000
Downtime, probability-weighted (assumed nine months): $675,000
Total rollover cost to price: about $5.0 million
A lender can ask you to fund that $5.0 million as an up-front leasing reserve, cover it through a cash sweep, or take it out of proceeds. Which one applies is a negotiated term, and it outweighs a small difference in coupon: on a $75 million loan, 10 basis points of rate is $75,000 a year, a fraction of a $5.0 million reserve.
When does a conversion exit change the underwriting?
A conversion exit changes the underwriting when the building's office cash flow cannot carry the loan on its own and the lender is asked to credit an alternative business plan, and in Manhattan that plan often runs through the 467-m property tax exemption for office-to-rental conversions, whose deadlines and affordability rules a lender reads closely.
The NYC Department of Housing Preservation and Development (HPD) program page says the exemption covers conversions of non-residential buildings, other than hotels and other class B multiple dwellings, into rental buildings of six or more units, where the conversion commenced after December 31, 2022 and on or before June 30, 2031 and is completed on or before December 31, 2039. At least 25% of the units must be affordable, at least 5% at 40% of Area Median Income, with a weighted average no higher than 80% of AMI, and the affordable units are permanently subject to rent stabilization.
The timing rule is the one that matters to a lender. HPD says a building must commence construction before applying, that the application cannot be filed earlier than the completion date and must be filed no later than one year after it, and that benefits are applied retroactively. A lender sizing an acquisition loan on a conversion fallback is therefore crediting a tax exemption that has not been granted and cannot be applied for until the work is done.
The Comptroller's fiscal note adds the economics. It says the program exempts property tax for up to three years during construction and for between 25 and 35 years afterward depending on the building permit date, with longer schedules for earlier start dates, and provides deeper exemptions in Manhattan south of 96th Street. It requires at least 50% of the completed building area to come from the pre-existing building.
For an office buyer, a conversion fallback supports the acquisition loan only when it is priced, down to the construction start date the plan needs under the June 30, 2031 commencement deadline. For the full capital stack on the conversion itself, see how to finance an office-to-residential conversion.
How do you get a Manhattan office acquisition loan placed?
You get a Manhattan office acquisition loan placed by sending one complete package, with the rent roll, the concession schedule, a priced rollover reserve and a costed conversion fallback, to many lenders at once, so the quotes compete on proceeds and structure instead of on how hard each lender haircuts the in-place income.
Option 1, the brokerage route (our pick; YieldStack publishes this guide): YieldStack is an AI-native commercial mortgage brokerage that arranges financing for commercial real estate investors. Software matches the deal against 20,000+ loan programs and compares the options; human brokers structure the deal, negotiate on the borrower's side and carry it toward closing. The median first offer arrives in under an hour, from an institutional lender. It costs Zero upfront to submit a deal and review offers; YieldStack's broker fee is 0.50–1.00% of the loan amount and is paid only at closing. Every credit decision is made by the lender; YieldStack arranges the introductions and negotiates on the borrower's side, and no loan, rate, or closing is guaranteed.
Why it ranks first for this deal: a Manhattan office file turns on how each lender treats rollover, concessions and the conversion fallback, and those are terms a broker negotiates on the borrower's side, while the software compares programs across the full catalog instead of one credit box.
Option 2, a direct lender relationship: a bank or lender you already know gives you one credit view and one set of reserve terms, and you negotiate the rollover haircut and the concession treatment alone.
For a Manhattan office purchase, the package that gets clean quotes carries the facts the sizing turns on:
- Rent roll by tenant, with suite, square footage, lease start and expiry, renewal options and current rent
- Every lease and amendment, with the free rent, work letter and leasing commissions still owed
- Net effective rent for each lease signed in the last two years
- A rollover schedule for leases expiring before the loan matures, with your renewal assumptions
- Trailing 12-month operating statement and the current-year budget
- If a conversion is the fallback: floor plates, a zoning review, a conversion budget and the 467-m affordability math
When it is ready, send the Manhattan office acquisition for review. Local context is on the Manhattan market hub.
The bottom line
Finance a Manhattan office purchase in 2026 on the income the building has today, not on the leasing headlines. Availability is at its lowest since 2020, but in its New York District report, the Fed's Beige Book says multiple contacts saw commercial property sales slow in recent weeks and small- to medium-sized banks tightened commercial mortgage standards slightly. Price debt yield, rollover reserves and concessions before a lender does, and cost the 467-m fallback, with its June 30, 2031 commencement deadline, if office income alone cannot carry the loan.